All Categories
Featured

Why to Use IUL for Retirement Planning
1 Rates are based on the typical month-to-month premium for Georgia Direct Premium rates industry Class A; Aflac Term Life Insurance TERM LIFE POLICY - Series 860000; Premiums may differ by coverage type, account, state of concern, and the election of additional/optional benefits. Content within this short article is provided for basic informative purposes and is not supplied as tax, legal, health, or monetary guidance for any person or for any particular circumstance. For complete details, consisting of availability and costs of Aflac insurance, please contact your regional Aflac agent/producer.
In Delaware, Policies A68200, A68300 & A68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400.
HMO vs PPO Health Insurance Plans
Not readily available in Delaware, Idaho, New Mexico, New York City, Oregon or Vermont. B61000, Juvenile series: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania, Texas & Virginia, Policies: ICC18B61JWO & ICC18B61JTO. In Delaware, Policies B61JWO & B61JTO. Q60000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania & Texas, Policy ICC18Q60200M. In Delaware, Policy Q60200M.
Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK.
Policies and riders may also include a waiting duration. Refer to the exact policy and rider types for advantage details, meanings, restrictions and exemptions. Premiums are ensured by CMFG Life Insurance Coverage Business.
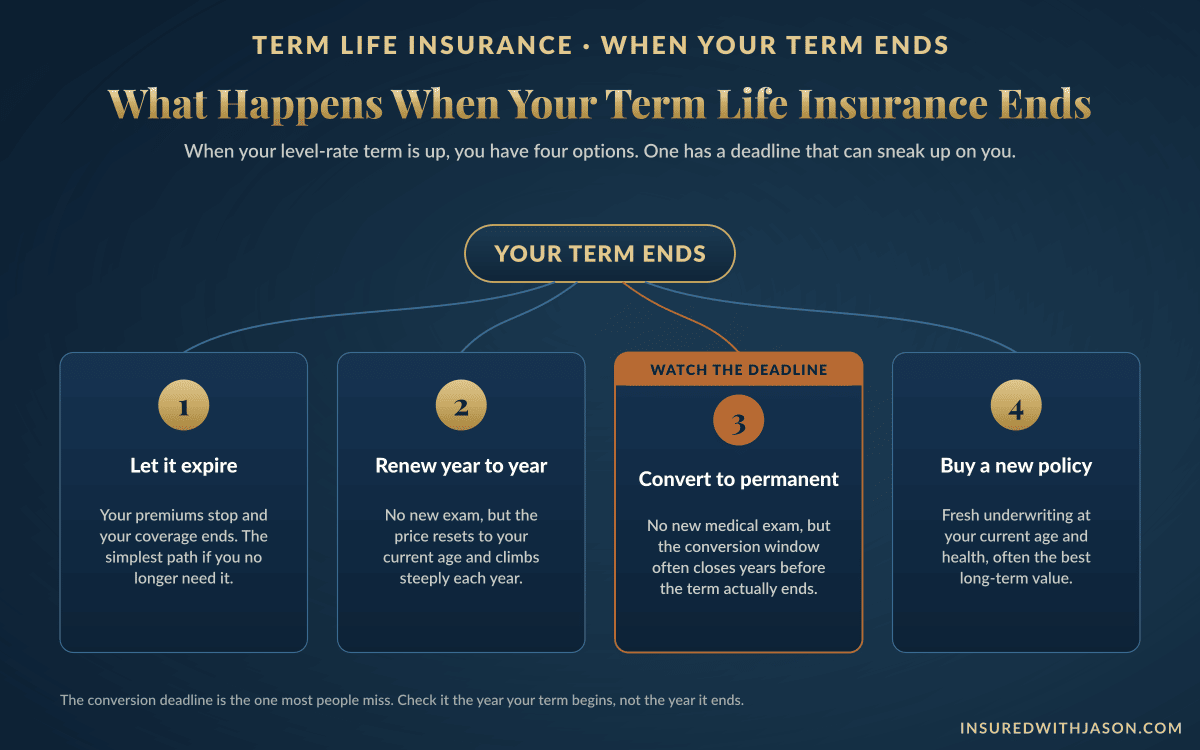
Why to Use IUL for Retirement Planning
* Based on your health and other elements impacting your insurability, you might be rejected coverage. Mon. Fri. 7 am9 pm; Sat. 8 am4 pm(CST)Your approval for this product is based upon your responses to the questions on the application and details we acquire from other sources. Please see your policy or contact us for details. The insurance used is not a deposit, and is not federally insured, sold or guaranteed. Product and functions may not be offered in all states. Lots of people are waiting till later on in life to start families. If you're one of them and you postpone buying life insurance up until you have children, it could cost you the opportunity of securing a low premium. Even if you don't yet have kids to secure, life insurance can cover your personal financial obligations, medical expenses, home mortgage, lost wages, and even funeral costs. Your health status is among the most important elements when determining term life insurance coverage rates.
Common Annuity MythsThe healthier you are, the less you pay, so getting life insurance coverage at a more youthful age can be helpful. As you age, the threat of establishing health problems(such as cancer or diabetes)increase, and can result in higher premiums and sometimes even make it challenging to get coverage. Here is a complete rate breakdown demonstrating how premiums increase decade by decade.
AgeMonthly PremiumAnnual CostTotal Over 20 Years25$18$216 $4,32030 $21$252 $5,04035$26 $312$6,24040$36$432$8,64045$55$660$13,20050$85$1,020$20,40055$135$1,620$32,40060$215$2,580$51,600 AgeMonthly PremiumAnnual Cost25 $15$18030$ 18$21635$22$26440$30$36045$45$54050$68$81655$108$1,29660$175$2,100 Rates are price quotes. Real premiums depend on health, carrier, and state. The distinction in between buying at 30 vs. 50 is $64/month or $15,360 over 20 years for the very same protection.
Here is a 20-year level term rate chart throughout $250K, $500K, and $1M (male, Preferred Non-Smoker): Age$250,000$500,000$1,000,00030$14$21$3840$23$36$6550$52$85$15660$128$215$395 Doubling your coverage does double your premium a set policy cost is spread out throughout more protection, so $1M is generally far less than 2 the $250K rate. If you are picking between quantities, purchasing more protection while young is often the better worth.
Smokers normally pay the non-smoker premium at the very same age. The majority of carriers move you to non-smoker rates after tobacco-free, so stopping before you apply can cut your premium roughly in half.

Latest Posts
Direct Advice for Life Insurance Selection
Why Whole Insurance Builds Family Wealth
Selecting the 2026 Medicare Advantage Coverage